Interest Turns Into Bitcoin: 21bitcoin Pays 1.21 Percent on Euro Balances

Set Trending Topics as a preferred source on Google.
Anyone waiting to make their next Bitcoin purchase now gets paid for waiting at 21bitcoin. Starting today, the Salzburg-based Bitcoin scale-up is paying 1.21 percent a year on the euro balances in its customers’ accounts. The interest is paid either in euros or automatically, with no conversion fee, in Bitcoin. According to the company, this makes 21bitcoin the first provider in Europe to pass savings interest on directly in Bitcoin.
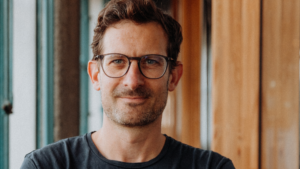
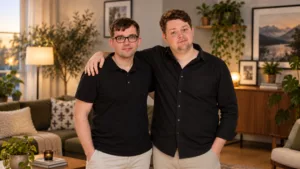
“Building Bitcoin wealth doesn’t start with the purchase, but with the euro that’s set aside for it. Until now, that money sat around earning nothing,” said Daniel Winklhammer, co-founder and chief executive of 21bitcoin. “This way, even the time between two purchases becomes part of building wealth.”
How the Offer Works
The key details, according to 21bitcoin:
- Interest rate: 1.21 percent a year on the entire euro balance, with no minimum amount and no lock-up period. The rate is variable.
- Waiting money earns too: Amounts earmarked for an open limit order or the next savings plan purchase also earn interest until the order is executed.
- Payout: Interest is calculated daily and credited monthly, in euros or converted into Bitcoin free of charge.
- Eligibility: The offer applies to all eligible new and existing customers.
The interest does not come from crypto activities but from a traditional bank. The euro balances are held in a trust account at Volksbank Raiffeisenbank Bayern Mitte, which has held a stake in 21bitcoin since 2023, separate from the company’s own assets. The bank pays interest on the money as an overnight deposit, and 21bitcoin says it passes the interest on without taking a margin. The company stresses that customer funds are not used for lending, proprietary trading or crypto yield strategies. It explicitly positions the model as a counterpoint to the yield promises that brought down several crypto providers in the past. Because the partner bank is based in Germany, the interest income is subject to German withholding tax on capital gains.
The Next Step After the Free Savings Plan
The interest offer complements Auto-Invest, 21bitcoin’s Bitcoin savings plan, which since the start of the year has charged no purchase fees after the first seven days. For 2027, the company has announced Bitcoin-backed loans, insured cold-storage custody with a publicly verifiable proof of reserves, and a multisig solution for long-term custody. For custody, 21bitcoin already works with the U.S. provider BitGo.
21bitcoin was founded by Daniel Winklhammer and Dominik Seibold and holds a crypto-asset service provider license under the E.U.’s MiCAR regulation from Austria’s Financial Market Authority. More than 100,000 users have traded over 650 million euros on the platform so far, according to the company.
How Good Is 1.21 Percent?
The 1.21 percent is well above what banks pay on checking accounts on average, but below the offers from neobrokers. On overnight deposits, banks in the eurozone pay households an average of just 0.28 percent, according to the latest interest rate statistics from the European Central Bank. New fixed-term deposits with maturities of up to one year pay 2.14 percent on average. The E.C.B. itself raised its deposit rate to 2.50 percent only in September.
Neobrokers pay considerably more. Trade Republic pays 2.50 percent on uninvested cash in Germany, linked to the E.C.B. deposit rate, according to Handelsblatt. In Austria, the Berlin-based company is even offering new customers 3 percent, with Brad Pitt as the face of its campaign. There, however, the interest is paid out in euros. Savers at 21bitcoin therefore give up part of the potential return and in exchange get automatic, fee-free conversion into Bitcoin.
In the DACH region, 21bitcoin also competes for Bitcoin savers with the Graz-based broker Coinfinity, which likewise focuses exclusively on Bitcoin, and with the Vienna-based crypto giant Bitpanda, which offers hundreds of digital assets.