Paying Without a Network: How Mastercard’s Offline Payments Work
Set Trending Topics as a preferred source on Google.
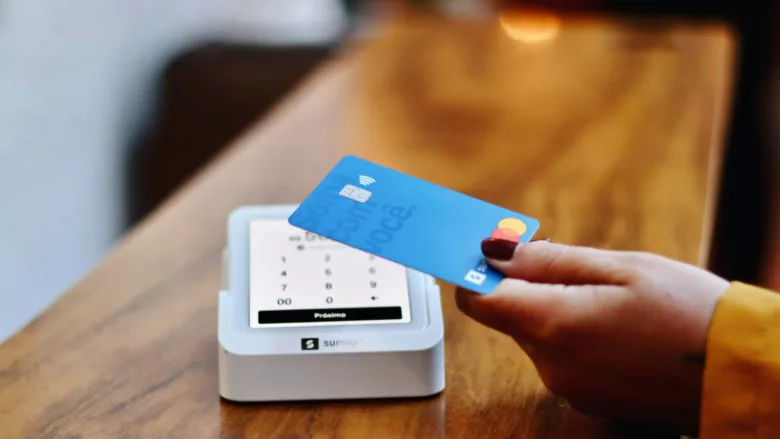
When the power goes out, the card should still work: Mastercard is requiring banks and merchants across Europe to make card payments possible even without a connection to the payment network. From February 2027, all newly issued Mastercard cards in Europe must be able to pay offline, and by May 2027, all newly installed payment terminals and all replacement devices must support it as well. The card company has just announced the move.
The Chip Makes the Call
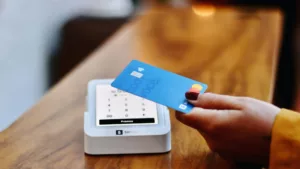
Normally, every card payment runs through the network: The terminal sends the data to the customer’s bank, which checks the account, the limit and the fraud risk and sends back a yes or no within seconds. If the connection fails, for example because the internet or the power grid goes down, nothing works. With offline payments, the chip on the card takes over that check itself.
To make this possible, the bank stores its rules on the chip in advance, meaning how much can be spent offline. According to Mastercard, up to €200 per transaction is possible, with each bank setting its own limit. If the terminal loses its connection, it asks the card instead. The chip compares the amount with its limits and approves or declines the payment. Under the EMV standard on which chip cards are based, the chip typically also keeps counters: It tracks how many offline payments have been made and what total has been spent since the last connection to the bank. Once a threshold is reached, the card requires an online check again.
PIN and Cryptography Instead of a Bank Server
Because no bank can check along in real time, Mastercard relies on chip and PIN for offline payments. The PIN is verified directly on the chip, so no bank server is needed. To prevent anyone from paying with a counterfeit card, the card proves its identity to the terminal cryptographically: The chip signs the transaction data with a secret key that never leaves the chip. The terminal verifies this signature using certificates it has stored in advance. A copied card without the real key is caught.
Once the payment is approved, the chip generates a digital proof known as a cryptogram. The terminal stores the transaction and the proof locally. As soon as the connection is back, it sends all collected payments to the banks for clearing, and only then is the money actually debited from the account. In industry jargon, this principle is called “store and forward.”
The Bank Carries the Risk
The system is not without drawbacks. With an offline payment, nobody checks whether there is actually enough money in the account, so the account can be overdrawn. Banks limit this risk through the limits on the chip, which is why Mastercard caps offline payments at €200. The feature is meant for essentials: groceries at the supermarket, fuel at the gas station, medicine at the pharmacy and tickets at vending machines. The terminal still needs electricity, of course. In Latvia, card payments continued during a storm-related network outage in shops that had their own generators, for example.
The push was triggered by the blackout in Spain and Portugal in April 2025, when about 55 million people suddenly could no longer pay digitally. Mastercard has already introduced offline payments in Denmark, Sweden, Estonia and Latvia. The company has not said which countries will follow next or when Austria and Germany will be included. Because the requirement applies only to new cards and new terminals, it is also likely to take years before the feature is widely available.
The Digital Euro Is Also Meant to Work Offline
Mastercard is not alone on this issue. After damage to Baltic Sea cables, the Nordic countries are working on their own contingency plans for payments. The European Central Bank is also planning an offline function for the digital euro that would allow money to be transferred directly from device to device. “When the power or network goes down, people still need to buy food, fuel and medicine,” said Brice van de Walle, executive vice president for core payments at Mastercard.